Operations
Noodles & Co bets on ramen, smaller footprint as Q3 comps climb
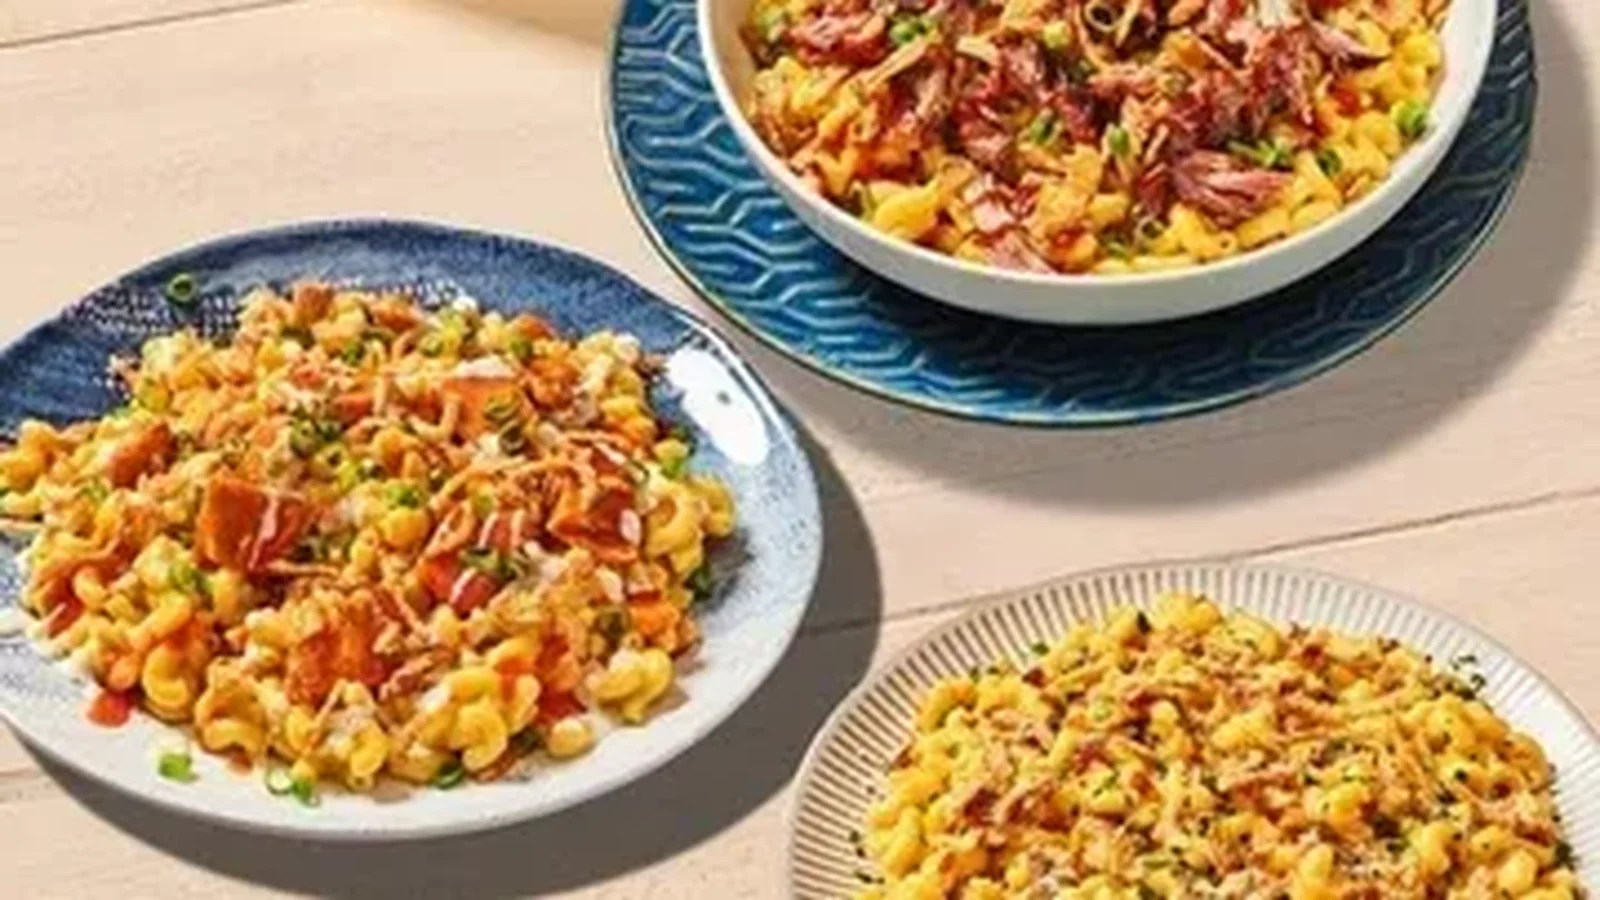
CEO Joe Christina, CEO of Noodles & Company, said the positive comps were thanks to a tested approach to menu innovation, which now includes ramen as a permanent category, and a closure program shutting dozens of underperforming restaurants and sending their sales to nearby locations.
November 16, 2026
 ChatGPT
 Grok
 Perplexity
 Claude
Noodles & Company posted its eighth straight quarter of positive same-store sales in the third quarter last week, but the bigger story behind the numbers is how the brand got there
CEO Joe Christina, CEO of Noodles & Company cited a tested approach to menu innovation, which now includes ramen as a permanent category, and a closure program shutting dozens of underperforming restaurants and sending their sales to nearby locations. It's a strategy he first laid out last year during the 2025 Q3 earnings call, and it appears to be working.
System-wide comparable restaurant sales rose 9.5% in the quarter. Company-owned restaurants were up 10.7% and franchise restaurants were up 4.9%. Comp traffic grew 7.8%, and average check rose 2.6%, including 1.9% effective pricing. Company average unit volumes grew 15.2% to $1.54 million.
Restaurant contribution margin rose to 16.7% from 13.2% a year ago. Adjusted EBITDA grew 34% to $8.7 million from $6.5 million. Total revenue fell $1.2 million to $120.9 million because the comp gains were offset by restaurant closures.
The net loss narrowed to $2.1 million, or 36 cents per diluted share, from $9.2 million, or $1.58 per diluted share, a year earlier. The loss included a $1.2 million non-cash impairment charge, mostly tied to the decision to close certain restaurants.
"This represents a step change in our operating model over the past year, as we benefited from the leverage of higher AUVs, together with more efficiencies on the cost side and the elimination of underperforming stores from our portfolio," Christina said Friday during the company's third-quarter earnings call.
Ramen gets a permanent spot
In October, Noodles made ramen a permanent menu category. The move builds on last year's Chili Garlic Ramen, which CFO Mike Hynes called the most successful LTO in the company's history.
The lineup features globally inspired flavors and comes at different price points to reach more value-focused guests. Christina said the permanent spot lets the brand rotate new ramen dishes onto the menu one after another. That way guests get the excitement of an LTO, and they can also count on always finding ramen, much as they do with the brand's mac category.
"With ramen now a permanent part of our menu, we have established yet another platform for continued culinary innovation," Christina said.
Early results are encouraging. During the October period, ramen reached a double-digit share of the product mix and helped deliver 5.5% comparable sales growth, against an 8% comp in October 2025, when Chili Garlic Ramen launched.
"This is further evidence that the sales gains and margin improvements we have realized over the last 12 months are sustainable and have created a new baseline of AUVs and restaurant profitability for our system," Hynes said.
Restaurants had made ramen before, but the brand still treated the launch like a new LTO. Training started in September.
"While there was some muscle memory at the restaurant because we had ramen throughout 2025 and the beginning of 2026, we approached the training like an LTO to make sure that restaurants are ready throughout the training process, the supply chain is ready and marketing is ready," Christina said.
Marketing pushed hard in the first couple of weeks to build awareness and get guests to try the dishes. From here, the company plans to "continue to pulse it, continue to build awareness and trial," as it does with mac and cheese, Christina said.
Ramen also gives guests a lower-priced option without dragging down the check, according to Hynes. Two of the current dishes come with a set protein, and one comes without.
"Right now, they're not hurting our average check at all," Hynes said. "We do have one that does not have a curated protein, and that's, I think, attractive from an entry point perspective from a guest perspective."
Comfort food, tested first
Ramen is just one piece of a larger menu overhaul. Christina said Noodles has become more deliberate about innovation over the past year. Dishes go through a testing process with guest feedback at every stage before they reach the full menu.
In August, Noodles added Baked Cheese Tortelloni to its baked lineup. The campaign also lifted trial and sales of Baked Chicken Parm and Garlic Cream Tortelloni.
"Of the new guests who tried Baked Cheese Tortelloni, we saw the highest return rate among dishes launched this year, which showed the opportunity for approachable, familiar flavors to encourage trial and bring guests back," Christina said.
He said the launch worked partly because culinary, operations, supply chain and marketing teams worked more closely together, from developing the dish to preparing restaurants and promoting it. Noodles has also been reinforcing operational basics through more consistent training, restaurant evaluations and closer work between company and franchise restaurants.
On marketing, the brand is combining national advertising, digital and social media, influencer partnerships and local restaurant marketing. Christina said the company's latest marketing mix modeling estimated that marketing contributed a meaningful increase in traffic and is helping bring in first-time guests.
What's on the 2027 menu
Through the first half of the year, Noodles will add more products across its Asian, Italian and mac and cheese categories. Ramen testing now underway will shape new rotations for the back half of the year.
"The innovation team is doing a great job, and our testing restaurants are delivering us information at a much higher rate so that we can make good decisions for 2027," Christina said.
Closing stores to grow sales
The other half of the turnaround is a smaller footprint. In the third quarter, Noodles closed 12 company-owned restaurants and two franchise restaurants, and opened one franchise restaurant.
Christina said the closure program has led to "a more permanent transfer of predominantly off-premise sales to nearby restaurants." The company estimates that sales moving from recently closed restaurants added about 300 basis points to third-quarter company comps.
"This creates an ongoing increase to the AUVs of the restaurants that were in proximity to the closed restaurants and contributes to restaurant contribution margin growth," Hynes said.
The smaller store count also cut occupancy costs to $9.8 million in the quarter, down from $11.1 million a year earlier.
For the full year, Noodles expects to close 34 to 36 company-owned restaurants and seven to eight franchise restaurants, and to open one new franchise restaurant.
The company tightened its 2026 revenue guidance to $485 million to $495 million. Asked why the top end came down, Hynes said the biggest factor was closures happening sooner than planned.
"Our total closures for the full year are within our original guidance range, but we did pull forward some, which is impacting the overall revenue line, but not hurting our profitability," he said.
Closures winding down
The program is nearly done. Hynes said the company has no firm number for 2027, but its current thinking is 10 to 15 closures next year. Some of those will be natural lease expirations rather than early closures under the portfolio optimization program.
"It is winding down," Hynes said. "We are getting to the end of the process."
Paying down debt
Noodles ended the quarter with $1.5 million in available cash and $101 million in debt, down $9.2 million since the end of 2025. The company still expects positive free cash flow in 2026 and a year-end debt balance of about $100 million, which would put debt below three times adjusted EBITDA.
The company also announced an amendment to its credit facility that extends the maturity date to Nov. 30, 2027, among other changes. Hynes said the extension, along with better business results, "provides additional flexibility as we continue our review of strategic alternatives."
Full-year guidance also calls for:
- Comparable restaurant sales growth of 9% to 10%
- Restaurant contribution margin of 16% to 16.7%.
- Adjusted EBITDA of $35 million to $37 million.
- Capital expenditures of $8.5 million to $9.5 million.
"We have accomplished a great deal, but our work is far from complete," Christina said.
Related Media
Subscribe
Get the latest news and resources from Fast Casual.
Recent Posts
Recent Podcasts